

Economic pressures are changing how customers behave – with transformative impact on how they shop. In this three-part look at a baker’s dozen of datasets, we delve into how consumers view their own behaviour, what that means for brands and how they can react
Part 1 – the simple economics facing consumers and how that translates into shopping habits
Part 2 – how that translates into ‘spending occasions’ and what that means for loyalty in an AI assisted world
Part 3 – how brands need to rethink how they market to customers and where, ultimately, people actually buy things – and it’s not where you think
Part 2: Rising to the ‘spending occasions’
TL;DR ⬇️
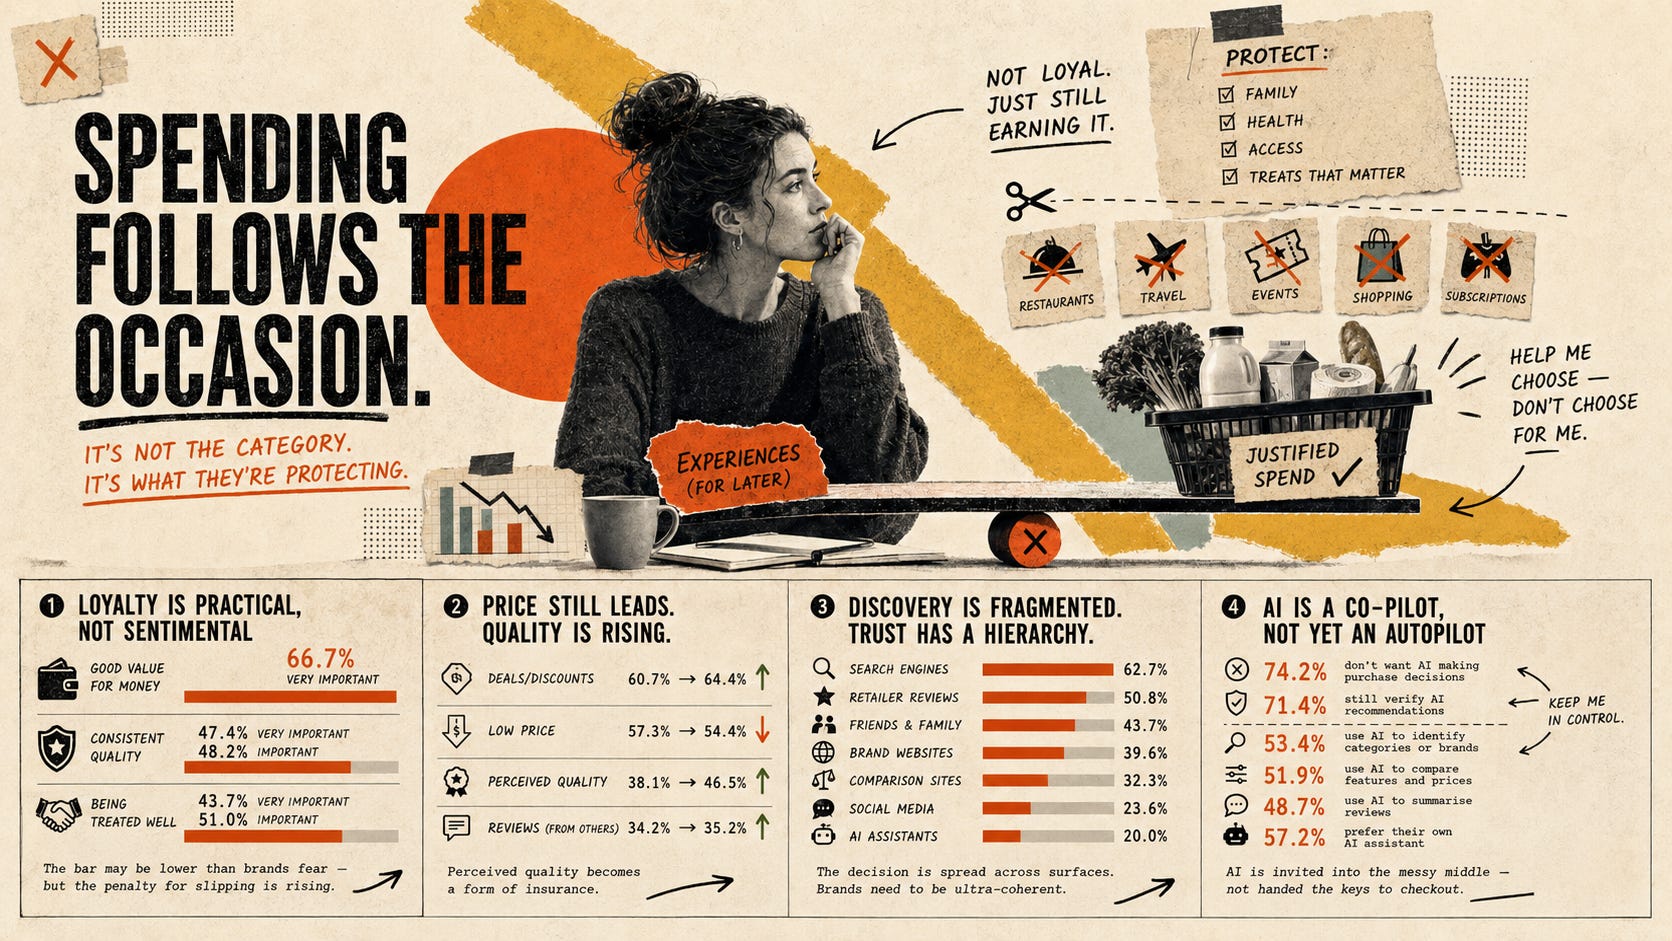
Consumers are not simply deciding what to buy, they are deciding what each category means to their life.
Essentials are protected: food, health, personal care, communication and insurance are relatively stable because they support household functioning, resilience, access and identity. More discretionary categories – restaurants, leisure, clothing and holidays – are under more pressure. But that does not mean they are dead, it means they need a stronger reason to exist in the customer’s budget.
That is the real lesson: brands should stop asking only, “Which category are we in?” and start asking, “What occasion do we help the customer protect?”
As a result, loyalty is changing too. Consumers are not staying with brands because of warm emotional attachment, they stay because the brand keeps delivering value, quality and decent treatment. Loyalty is less like love and more like a rolling contract: useful, but always up for renewal.
On the ‘everyday shelf,’ price still matters, but quality is rising fast. Consumers want deals, but not cheap disappointment and are looking for a better thing at a price they can defend.
Discovery is also fragmenting. Search, reviews, friends and family, brand websites, comparison sites, social media and AI are all part of the decision. This is not a funnel anymore, it is a committee.
And AI is already in the room. Consumers do not want it to make purchases for them, but they are happy for it to compare, summarise and organise the decision. The awkward bit for retailers? Many prefer their own AI assistant to a retailer’s chatbot.
The next battleground is trust: who does the customer believe is really working for them?
Contents
Loyalty is practical, not sentimental
The everyday shelf is still ruled by price, but quality is rising in importance
Discovery is fragmented, but trust still has a hierarchy
AI is a co-pilot, not yet an autopilot
The mounting economic pressures and the shifts it has inculcated in consumer habits is clear in the sector spending chart, below, that kicks off part two of our three parter Customers are not cutting back – they are cutting differently. And it shows just how the customer is sorting their world – and what a wake up call for brands and sellers across the board it is.
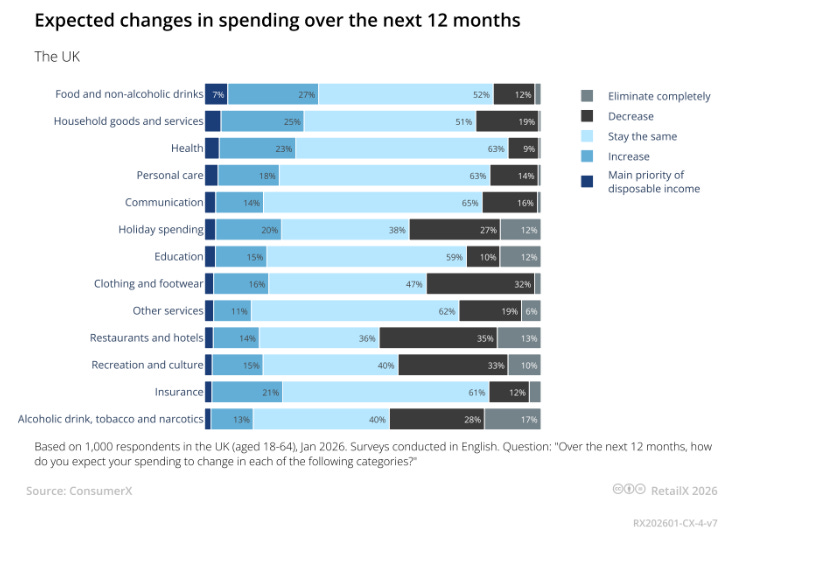
Food and non-alcoholic drinks are relatively protected: 27% expect to increase spending and 51.9% expect spending to stay the same. Health is also resilient, with 63.1% expecting spending to stay the same and 22.7% expecting spending to increase. Personal care, communication and insurance are largely stable.
The pressure sits more heavily on discretionary and experience categories. Restaurants and hotels see 35.1% expecting to decrease spend and 13% expecting to eliminate it completely. Recreation and culture sees 32.7% expecting to decrease and 9.8% expecting to eliminate. Clothing and footwear has 32.2% expecting to decrease. Holiday spending is particularly split: 19.6% expect to increase, but 27.1% expect to decrease and 12.1% expect to eliminate it completely.
At first glance, this looks like a sector ranking where essentials win, discretionary loses. But that is too simple.
What the data really shows is that categories are being reclassified by the customer according to their role in their life. Food is not just food; it is household functioning. Health is not just a category; it is resilience. Communication is not just a bill; it is access. Personal care may sit somewhere between necessity and identity. Holidays, restaurants and leisure are more vulnerable because they have to make a stronger case for themselves.
But vulnerable does not mean irrelevant, it means these categories need a better justification if spend is to be justified. This is why occasion-led thinking matters. A restaurant meal may be easy to cut in the abstract, but harder to cut if it is a birthday, anniversary, reunion or long-promised family treat. Clothing may be deferred until it becomes tied to work, school, identity or an event. Travel may be eliminated by some, protected fiercely by others.
The question for brands is not only, “Which category are we in?” It is, “What occasion do we help the customer protect?”
Loyalty is practical, not sentimental
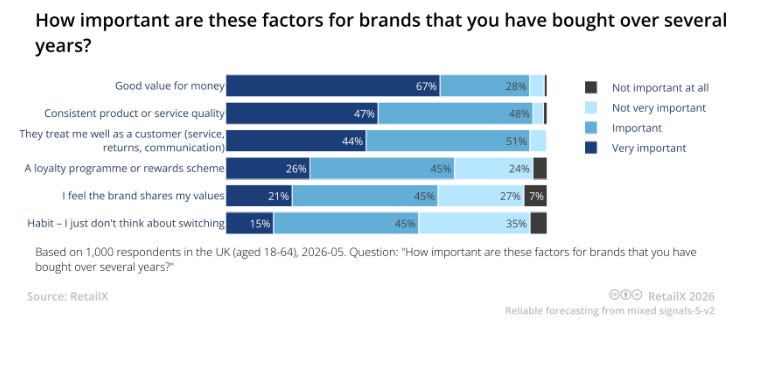
Against this backdrop, the loyalty chart above is almost comically unsentimental. For brands that consumers have bought over several years, 66.7% say good value for money is very important. Consistent product or service quality is very important to 47.4% and important to a further 48.2%. Being treated well as a customer through service, returns and communication is very important to 43.7% and important to 51%.
This is loyalty, but not love. It is tempting for brands to believe that long-term customers are emotionally attached. Some are, but the data suggests that much loyalty is really a rolling contract. The customer stays because the brand continues to deliver value, quality and decent treatment. But this is a constant state of probation rather than devotion.
This makes loyalty both more fragile and more useful than many brands assume. Fragile, because a customer who has bought for years may still leave if the terms of the relationship deteriorate. Useful, because the things that sustain loyalty are not mysterious. Customers are not asking to be dazzled. They are asking not to be disappointed.
There is something very revealing in the phrase, “They treat me well.” It does not sound like a grand brand promise. It sounds basic. Service that works. Returns that are not hostile. Communication that does not insult their intelligence. A sense that the brand remembers the relationship without exploiting it.
The bar for loyalty may be lower than brands fear, but the punishment for falling below it is rising.
The everyday shelf is still ruled by price, but quality is rising in importance
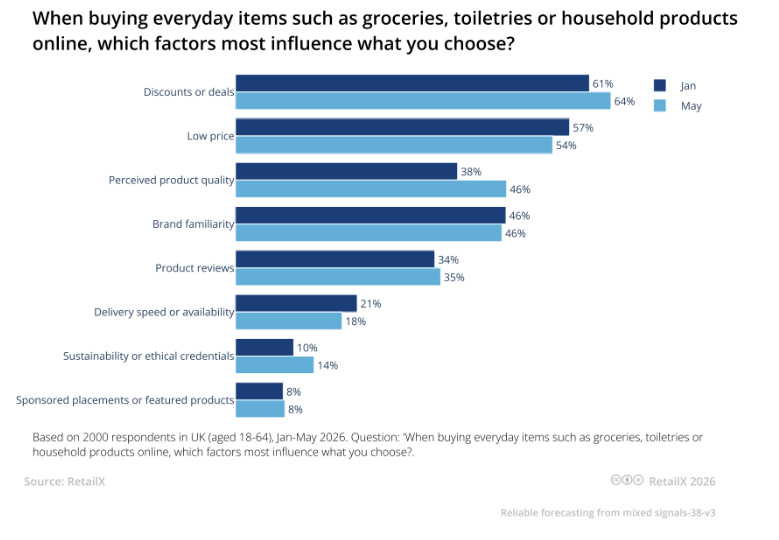
Everyday online shopping shows the same pragmatic intelligence. Discounts or deals are the most influential factor, rising from 60.7% in January to 64.4% in May. Low price remains high, but falls from 57.3% to 54.4%. Brand familiarity is broadly stable, slipping slightly from 46.4% to 45.7%. Product reviews edge up from 34.2% to 35.2%. But the stand-out movement is perceived product quality, which jumps from 38.1% to 46.5%.
This is a fascinating little contradiction. Discounts are more important, but low price is less important. Quality is much more important. The consumer is not saying: “Give me the cheapest thing,” they are saying: “Give me a better thing at a price I can defend.”
That is a very different buying mood than in recent years. It suggests consumers are becoming more experienced at navigating pressure. The first stage of inflation may push people towards cheaper choices. The second stage teaches them that cheap can be expensive if it fails, disappoints, runs out quickly, tastes worse, breaks sooner or creates hassle.
Perceived quality becomes a form of insurance.
This also explains why sponsored placements remain low as a claimed influence, at only 8.5%. Consumers do not like to think of themselves as influenced by promoted products, they prefer to believe they are choosing through price, deal, quality, familiarity and reviews.
That does not mean sponsored placements have no effect. It may mean their effect is often invisible to the customer. A promoted product can change what appears in front of them, but they still experience the final decision as their own. They see the deal, the rating, the brand, the product image and the price. The advertising has done its work before the customer names it as advertising.
Discovery is fragmented, but trust still has a hierarchy
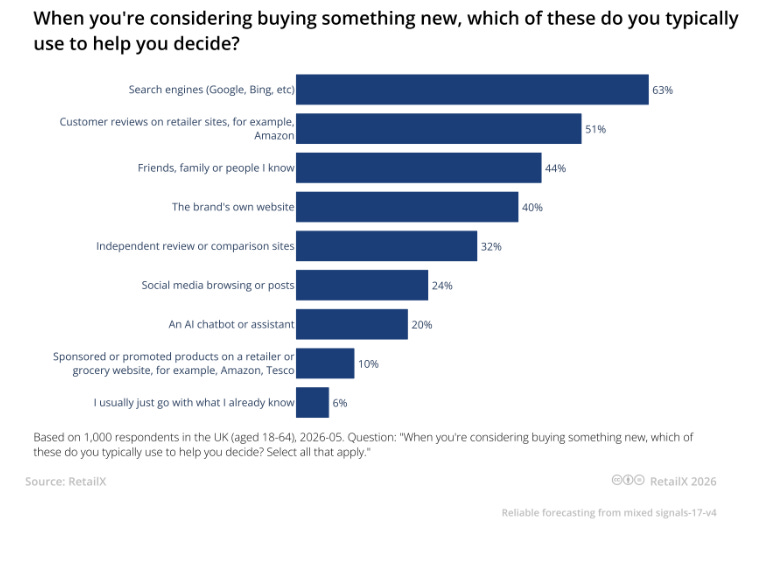
The discovery chart above shows just how fragmented decision-making has become. Search engines are used by 62.7% when considering something new. Customer reviews on retailer sites are used by 50.8%. Friends, family or people the consumer knows are used by 43.7%. The brand’s own website is used by 39.6%. Independent review or comparison sites are used by 32.3%. Social media browsing or posts are used by 23.6%. AI chatbots or assistants are already used by 20%. Sponsored or promoted products on retailer or grocery websites are used by 10.5%.
This is not a funnel, it is a committee. The modern consumer does not ask one source what to buy, they assemble evidence. Search shows what exists, reviews point to what other people regret, friends and family add social proof. Brand websites, meanwhile, provide official reassurance and comparison sites reduce the fear of missing a better option. Social media sits over this, creating desire and/or familiarity. And AI increasingly tidies the mess.
For brands, this is both an opportunity and a problem. The opportunity is that there are more places to influence the customer. The problem is that no single place controls the story. A brand can win the ad impression and lose the review. It can win search visibility and lose on comparison. It can build a beautiful website and be undermined by social chatter. It can optimise the retailer page and be filtered out by an AI assistant.
The customer’s decision is now distributed across surfaces. The brand’s job is not simply to be present, but to also be ultra-coherent.
AI is a co-pilot, not yet an autopilot
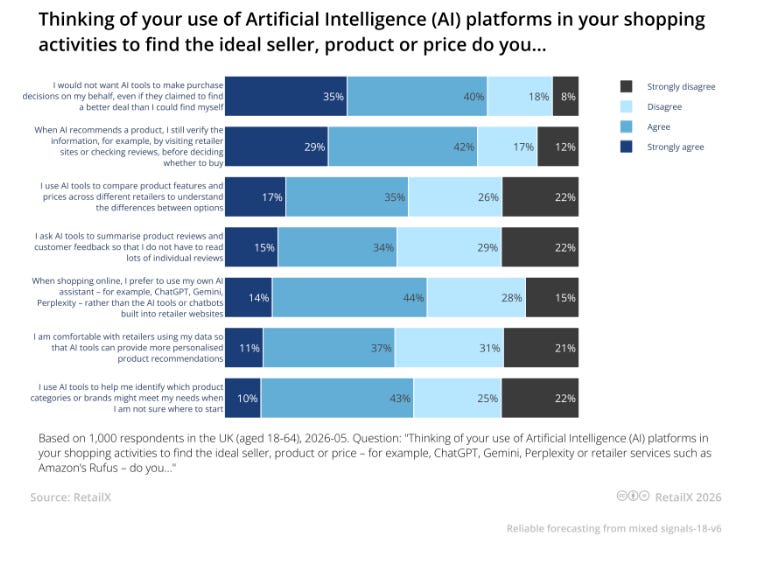
The AI chart may be the clearest sign of where consumer behaviour is going next. On the surface, consumers remain cautious, with some 74.2% agreeing or strongly agreeing that they would not want AI tools to make purchase decisions on their behalf – even if those tools claimed to find a better deal. Some 71.4% agree or strongly agree that when AI recommends a product, they still verify the information by visiting retailer sites or checking reviews before deciding whether to buy.
But beneath that caution, adoption is already substantial. Some 51.9% agree or strongly agree that they use AI tools to compare product features and prices across retailers. Some 48.7% use AI to summarise product reviews and customer feedback. Some 53.4% use AI to identify product categories or brands that might meet their needs when they are not sure where to start.
This is human-controlled delegation. Customers do not want AI to be the shopper, they want it to be a shopping accomplice. They will let it summarise, compare, organise and suggest. They will not yet let it decide. AI is being invited into the messy middle of the purchase journey, not handed the keys to the checkout.
The most commercially awkward finding is that 57.2% agree or strongly agree that, when shopping online, they prefer to use their own AI assistant, such as ChatGPT, Gemini or Perplexity, rather than the AI tools or chatbots built into retailer websites.
That should make retailers nervous. It suggests that consumers may accept AI assistance, but not necessarily from the seller. The customer wants an agent that feels like it is on their side. A retailer chatbot, however useful, may still feel like a salesperson. A personal AI assistant feels more like an adviser.
That distinction may become one of the defining commercial questions of the next decade: who does the customer believe is working for them? In part three we look at how brands need to rethink how they engage with customers as a result.
Our cross-sector commerce summit, CustomerX, takes place on 14 and 15 October, 2026 in London. Come to copy, collaborate or compete across sectors, to grow your share of the customer’s disposable income. Registration is open. From the Supernova Theatre, to workshops, via One-to-One partnering meetings and ThinkTanks, it’s a chance to move from the screen to real life commerce connection.
Other articles in this series include:
Customers are not cutting back – they are cutting differently

Economic pressures are changing how customers behave – with transformative impact on how they shop. In this three part look at a baker’s dozen of datasets, we delve into how consumers view their own behaviour, what that means for brands and how they can react